
Fraud is an intentional act of deception, concealment, or misrepresentation designed to obtain an unauthorised benefit or cause another person or organisation to suffer a loss. Fraud can involve money, property, financial statements, confidential information, business transactions, or the abuse of a position of trust. It may be committed by individuals, employees, executives, customers, suppliers, or organised criminal groups.
Fraud occurs in both physical and digital environments. Examples include phishing scams, investment fraud, financial statement manipulation, bribery, payroll fraud, fake invoices, and the unauthorised diversion of company assets.
Understanding fraud is essential for businesses, banks, auditors, compliance professionals, investigators, and individuals. Two disciplines play particularly important roles in identifying and investigating suspected fraud: fraud examination and forensic accounting. Although they overlap, they have different areas of emphasis, investigative techniques, and practical applications.
What Are the Main Elements of Fraud?
Fraud generally involves deliberate deception or concealment associated with an unauthorised benefit, a financial or other loss, or both. The precise legal elements depend on the type of fraud and the applicable jurisdiction.
Common characteristics of fraud include:
- Intentional deception: A person deliberately provides false information, conceals material facts, or misrepresents a transaction.
- Misuse of trust or authority: The perpetrator may exploit a professional position, business relationship, or victim’s confidence.
- Unauthorised benefit: The conduct is intended to obtain money, property, services, business advantages, or another benefit.
- Financial or other harm: The victim may experience financial losses, reputational damage, operational disruption, or loss of confidential information.
Not every financial loss or accounting error constitutes fraud. An error may arise from negligence or misunderstanding, whereas fraud involves the relevant dishonest intent required under the applicable legal framework. Investigators must examine the evidence before drawing conclusions about whether fraud has occurred.
What Are the Different Types of Fraud?
Fraud takes many forms, depending on the perpetrator, the victim, the method used, and the assets or information targeted. Five important categories are consumer fraud, financial statement fraud, corruption, asset misappropriation, and fraud involving confidential information or intellectual property. According to Indiaforensic, different type of frauds cause loss of more than $40 Billion.
1. Consumer Fraud
Consumer fraud occurs when individuals are deceived into transferring money, sharing sensitive information, purchasing unsuitable or nonexistent products, or participating in fraudulent schemes.
Common examples include:
- Phishing: Fraudulent emails, messages, or websites designed to obtain passwords, banking credentials, or personal information.
- Investment fraud: False promises of guaranteed returns, fictitious investment opportunities, or Ponzi schemes.
- Pyramid schemes: Recruitment-driven arrangements that may misrepresent their business model and depend on payments from new participants.
- Impersonation scams: Criminals pretending to represent banks, government agencies, legitimate businesses, or trusted individuals.
- Telemarketing and online shopping fraud: Misleading sales practices involving fake offers, nonexistent products, or unauthorised charges.
Consumer fraud often exploits urgency, trust, fear, or the expectation of unusually high returns. Investigating these schemes may require transaction tracing, digital evidence collection, analysis of communications, and identification of the ultimate beneficiaries.
2. Financial Statement Fraud
Financial statement fraud occurs when an organisation or an individual deliberately misrepresents financial information to mislead investors, lenders, regulators, auditors, or other stakeholders.
The objective may be to exaggerate profitability, conceal financial difficulties, satisfy lending conditions, inflate share prices, or secure performance-based compensation.
Common techniques include:
- Fictitious revenue: Recording sales or income that never occurred.
- Revenue manipulation: Recognising revenue prematurely or manipulating the timing of transactions.
- Asset overstatement: Inflating the reported value of inventory, receivables, or other assets.
- Liability understatement: Concealing debts, expenses, provisions, or contractual obligations.
- Improper expense recognition: Omitting expenses or capitalising costs that should be recognised as expenses.
- Misleading disclosures: Withholding material information about related-party transactions, financial risks, or business performance.
Forensic accountants examine financial statements, accounting entries, supporting documents, transaction patterns, and relationships between reported figures and underlying business activity. Analytical techniques can help identify anomalies that warrant further investigation.
3. Corruption and Bribery
Corruption involves the abuse of entrusted power or position for improper gain. Bribery is one form of corruption and generally involves offering, promising, giving, requesting, or accepting an improper advantage.
Examples include:
- Paying a procurement officer to influence a contract award.
- Accepting kickbacks from suppliers.
- Offering an improper payment to secure a regulatory approval.
- Manipulating tender specifications to favour a particular bidder.
- Using intermediaries or sham consultancy agreements to disguise improper payments.
Corruption investigations may involve reviewing procurement records, vendor relationships, invoices, payment flows, communications, beneficial ownership, and conflicts of interest.
A transaction that appears commercially legitimate on its face may conceal an improper arrangement. Investigators therefore examine the substance of the transaction, the services actually provided, and the identity of the ultimate beneficiaries.
4. Asset Misappropriation
Asset misappropriation occurs when a person wrongfully takes, diverts, or uses assets entrusted to an organisation or another party. It is a common category of occupational fraud.
Examples include:
- Cash theft: Taking cash before it is recorded in the accounting system.
- Payroll fraud: Creating fictitious employees, manipulating hours, or diverting salary payments.
- Billing fraud: Submitting false invoices through fictitious suppliers or unauthorised payments.
- Expense reimbursement fraud: Claiming personal expenses as business expenses or submitting duplicate claims.
- Inventory theft: Removing stock or manipulating inventory records to conceal shortages.
- Cheque and payment tampering: Altering payment instruments or diverting funds.
- Unauthorised asset use: Using company vehicles, equipment, software, or other resources for personal benefit in violation of applicable rules.
Asset misappropriation can be difficult to detect when transactions are poorly documented or internal controls are weak. Reconciliation, segregation of duties, access controls, transaction monitoring, and independent reviews help identify suspicious activity.
5. Trade Secret Theft and Intellectual Property Misappropriation
Trade secret theft involves the unauthorised acquisition, use, or disclosure of confidential business information that qualifies for legal protection. Such information may include manufacturing processes, proprietary algorithms, customer lists, pricing strategies, formulas, or product-development plans.
For example, an employee might transfer confidential customer data to a competitor or disclose a proprietary manufacturing process without authorisation.
However, trade secret theft is not automatically fraud in every legal context. The conduct may instead, or additionally, constitute a breach of contract, theft, unlawful disclosure, or intellectual property misappropriation, depending on the facts and applicable law.
Investigations may require examination of access logs, file transfers, emails, device activity, confidentiality agreements, and the chain of custody of digital evidence.
What Is Fraud Examination?
Fraud examination is a systematic process of investigating suspected fraud, evaluating evidence, determining what happened, and documenting findings. It may begin following a complaint, whistleblower report, audit finding, suspicious transaction, regulatory referral, or other indication of possible misconduct.
Fraud examination does not require investigators to assume that fraud has already been proven. Instead, they establish the facts and assess whether the available evidence supports the allegation.
A fraud examination may involve the following activities:
- Reviewing the allegation: Understanding the reported misconduct, relevant parties, transactions, and potential losses.
- Preserving evidence: Securing documents, electronic records, financial data, and other relevant material.
- Analysing transactions: Identifying unusual payments, unexplained adjustments, suspicious relationships, and control weaknesses.
- Conducting interviews: Gathering information from complainants, witnesses, employees, and other relevant individuals.
- Testing explanations: Comparing statements and explanations against documentary and digital evidence.
- Documenting findings: Preparing an objective report that distinguishes established facts, supporting evidence, limitations, and unresolved questions.
Fraud examiners must maintain objectivity and avoid treating allegations as proof. Their role is to investigate and report findings, not to determine guilt where that decision belongs to a court or another authorised body.
Depending on the case, fraud examination may also identify weaknesses in internal controls and recommend measures to reduce the risk of recurrence.
What Is Forensic Accounting?
Forensic accounting is the application of accounting, financial analysis, investigative techniques, and relevant legal knowledge to examine financial information for use in disputes, investigations, or legal proceedings.
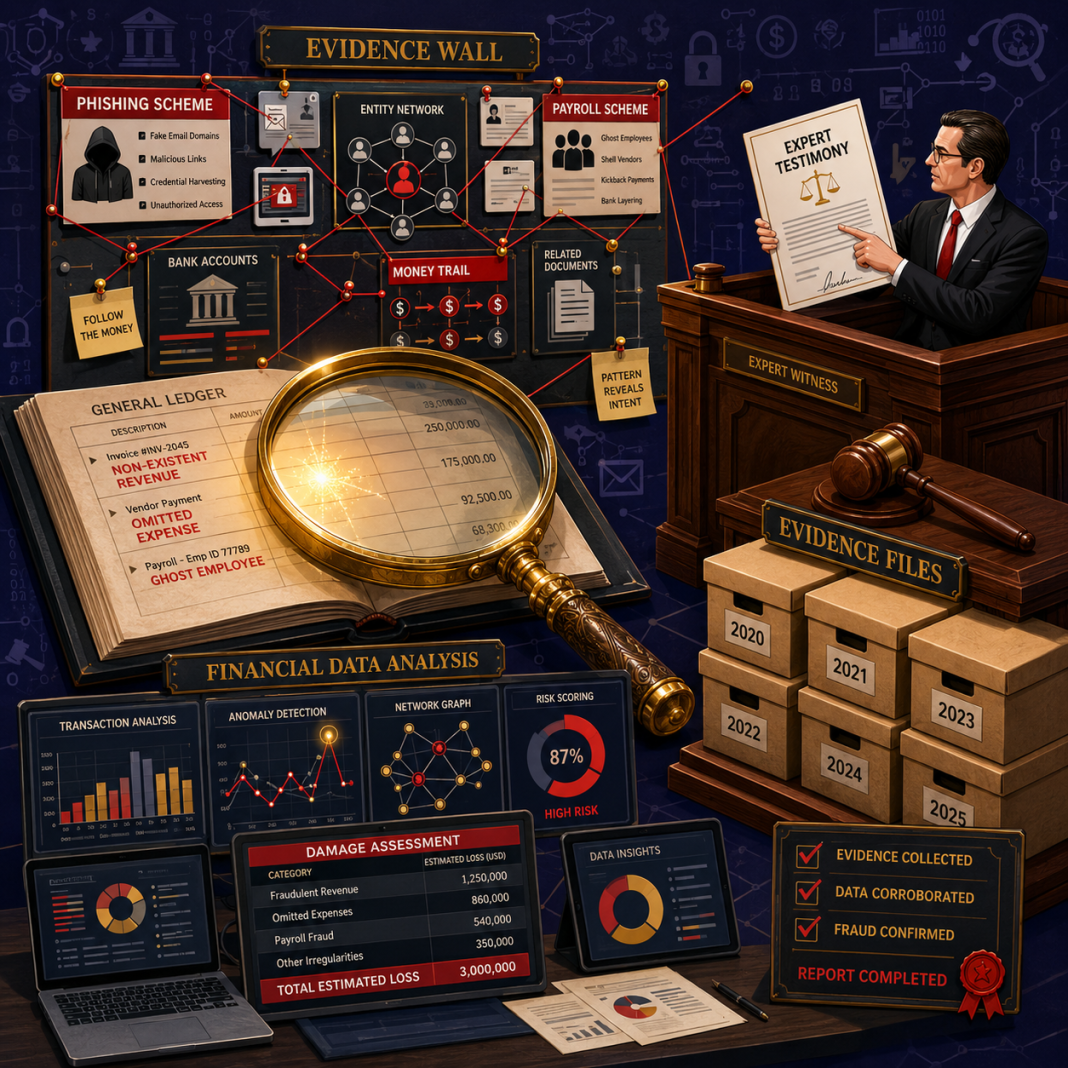
Forensic accountants analyse financial records to reconstruct transactions, identify irregularities, quantify losses, trace assets, and explain complex financial evidence.
Their work may support fraud investigations, civil litigation, insurance claims, shareholder disputes, insolvency proceedings, business valuations, and other matters involving financial evidence. Forensic accounting is not limited to cases in which fraud has already been confirmed.
Typical forensic accounting activities include:
- Analysing general ledgers, bank statements, invoices, contracts, and financial statements.
- Tracing the movement of funds between individuals, companies, and accounts.
- Reconstructing incomplete or manipulated accounting records.
- Quantifying financial losses and assessing competing damages calculations.
- Examining related-party transactions and potential conflicts of interest.
- Supporting legal teams with financial analysis, reports, and expert testimony where appropriate.
For example, when a company suspects that a senior employee has diverted funds through fictitious suppliers, a forensic accountant may examine supplier records, bank transfers, invoices, accounting entries, and beneficial ownership information to reconstruct the payment trail and estimate the loss.
Forensic accounting can therefore help transform complex financial data into evidence that investigators, lawyers, management, regulators, or courts can evaluate.
Professionals seeking structured training in this field can explore the Certified Forensic Accounting Professional (CFAP) programme.
Fraud Examination vs. Forensic Accounting: What Is the Difference?
Fraud examination and forensic accounting are closely related disciplines, but they are not interchangeable. Fraud examination focuses on investigating suspected misconduct, while forensic accounting focuses on analysing and interpreting financial evidence. Their responsibilities frequently overlap.
| Comparison | Fraud Examination | Forensic Accounting |
|---|---|---|
| Primary focus | Investigating suspected fraud and determining what the evidence establishes | Analysing financial information for investigations, disputes, and legal purposes |
| Starting point | An allegation, complaint, red flag, or other indication of possible misconduct | A suspected irregularity, financial dispute, investigation, or other need for financial analysis |
| Main objective | Establish the facts, assess the allegation, and identify the method and parties involved where evidence permits | Reconstruct transactions, trace funds, quantify losses, and explain financial findings |
| Typical techniques | Interviews, document examination, investigative enquiries, evidence evaluation, and transaction testing | Financial statement analysis, ledger examination, transaction reconstruction, asset tracing, and loss quantification |
| Evidence examined | Financial, documentary, testimonial, digital, and other relevant evidence | Primarily financial and accounting evidence, supplemented by other relevant information |
| Potential outcomes | An investigative report, referrals, control recommendations, or evidence supporting further action | A financial analysis report, damages assessment, transaction reconstruction, or expert evidence |
| Professional settings | Corporate investigations, compliance, law enforcement, internal audit, and specialist investigation practices | Accounting firms, consulting practices, corporate investigations, litigation support, and dispute resolution |
The distinction is one of emphasis rather than an absolute division of responsibility. A fraud examiner may perform financial analysis, and a forensic accountant may investigate suspected fraud. Both may contribute evidence to civil or criminal proceedings.
The findings of either professional do not automatically establish criminal liability. Legal conclusions depend on the applicable law, the admissible evidence, and the decisions of the competent authority.
How Do Fraud Examination and Forensic Accounting Work Together?
Consider a company that discovers unexplained payments to a supplier that appears to have no legitimate business operations.
A fraud examination may begin with a review of the complaint, interviews with relevant employees, examination of procurement approvals, and investigation of relationships between the supplier and company personnel.
Forensic accounting may then reconstruct the payments, reconcile invoices against accounting entries, examine bank records, trace the flow of funds, and calculate the potential financial loss.
The combined investigation may establish whether the transactions were genuine, identify suspicious conduct, document control failures, and provide evidence for management, legal counsel, regulators, or law enforcement.
This example illustrates why the two disciplines are complementary. Investigative work establishes the context and evidential narrative, while financial analysis explains the transactions and their monetary implications. In practice, these activities often proceed in parallel.
What Skills Are Required for Fraud Examination and Forensic Accounting?
Professionals working in these fields need a combination of analytical, investigative, accounting, and communication skills.
Important capabilities include:
- Accounting and financial analysis: Understanding financial statements, ledgers, reconciliations, and transaction flows.
- Investigative reasoning: Developing hypotheses, testing explanations, and evaluating conflicting evidence.
- Data analysis: Identifying anomalies, unusual relationships, duplicate payments, and suspicious transaction patterns.
- Interviewing and evidence handling: Obtaining relevant information while preserving the integrity and reliability of evidence.
- Legal and regulatory awareness: Understanding applicable reporting obligations, procedural requirements, and evidentiary limitations.
- Report writing and communication: Presenting complex findings clearly, objectively, and in a form appropriate for the intended audience.
These skills are relevant to accountants, auditors, banking professionals, compliance officers, investigators, lawyers, and other professionals involved in financial crime prevention or investigation.
Professional Training in Fraud Examination and Forensic Accounting
Specialist education can help professionals develop the knowledge required to recognise fraud indicators, analyse financial evidence, and understand investigative methodologies.
The Certified Forensic Accounting Professional (CFAP) programme covers forensic accounting concepts and related investigative applications. It is relevant to individuals interested in developing knowledge of financial analysis, fraud investigation, and litigation support.
For banking professionals seeking training in bank-related fraud and financial investigations, the Certified Bank Forensic Accountant programme is another resource to explore. Prospective learners should review the current course syllabus, eligibility requirements, and certification details before enrolling.
Training should complement, rather than replace, applicable professional qualifications, practical experience, and jurisdiction-specific legal requirements.
Frequently Asked Questions About Fraud
What is fraud in simple terms?
Fraud is deliberate deception intended to obtain an unauthorised benefit or cause another party to suffer harm. Examples include investment scams, false invoices, bribery, payroll fraud, and deliberate manipulation of financial statements.
What are the five main types of fraud?
Five commonly discussed categories are consumer fraud, financial statement fraud, corruption and bribery, asset misappropriation, and fraud involving confidential information or intellectual property. Other classifications include insurance fraud, tax fraud, identity fraud, procurement fraud, and cyber-enabled fraud.
What is the difference between fraud and an accounting error?
An accounting error is an unintentional mistake or omission. Fraud involves intentional dishonest conduct, concealment, or misrepresentation as established by the applicable legal framework. Investigators must assess the evidence before deciding whether an irregularity is an error, misconduct, or fraud.
What is the purpose of fraud examination?
The purpose of fraud examination is to investigate suspected fraud, establish the relevant facts, evaluate evidence, identify methods and responsible parties where possible, and document findings. It may also identify control weaknesses and support appropriate remedial action.
What is the purpose of forensic accounting?
Forensic accounting applies accounting and financial investigative techniques to matters that may involve litigation, suspected fraud, financial disputes, or other proceedings. It can help reconstruct transactions, trace assets, quantify losses, and explain financial evidence.
Can forensic accountants investigate suspected fraud?
Yes. Forensic accountants can investigate suspected fraud and financial irregularities. They may analyse accounting records, trace transactions, identify anomalies, and work alongside fraud examiners, auditors, lawyers, and other investigators.
Are fraud examination and forensic accounting the same?
No. Fraud examination concentrates on investigating suspected misconduct, while forensic accounting concentrates on analysing financial evidence and explaining its implications. The disciplines overlap, and professionals may perform activities associated with both.
Is fraud a civil or criminal offence?
Fraud may give rise to civil claims, criminal proceedings, or both, depending on the conduct and the applicable jurisdiction. Civil proceedings may seek remedies such as damages or recovery of assets, while criminal proceedings may result in penalties imposed by a court. The precise legal classification depends on the facts and relevant law.
How can organisations prevent fraud?
Organisations can reduce fraud risk through effective internal controls, segregation of duties, independent reconciliations, supplier due diligence, access controls, whistleblowing mechanisms, transaction monitoring, and timely investigation of suspicious activity. Prevention also requires management oversight and a culture that supports ethical conduct.
Conclusion
Fraud is a broad category of intentional deceptive conduct that can affect individuals, businesses, financial institutions, and public organisations. Recognising its different forms is the first step towards effective detection, investigation, and prevention.
Fraud examination helps establish what happened and evaluate the evidence surrounding suspected misconduct. Forensic accounting provides the financial analysis needed to reconstruct transactions, trace assets, quantify losses, and communicate complex financial findings.
Together, these disciplines support evidence-based investigations, informed legal and business decisions, and stronger fraud risk management. Developing expertise in fraud examination and forensic accounting can help professionals contribute to the detection of financial misconduct, the protection of organisational assets, and the integrity of financial reporting.